
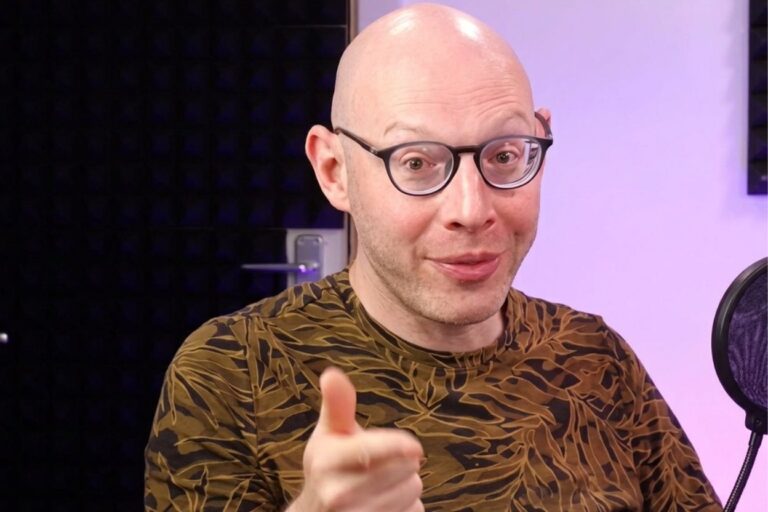
In the complex world of British fiscal policy and legal accountability, dan neidle stands as a pivotal figure. He has successfully bridged the gap between the insular world of “Big Law” and the public-facing sphere of investigative journalism. By transitioning from a high-powered partner at a prestigious global law firm to the founder of a non-profit think tank, he has fundamentally changed how the public perceives tax transparency. His journey remains a compelling study in professional integrity and the pursuit of institutional reform.
The Professional Ascent of Dan Neidle
For nearly twenty-five years, dan neidle built an impressive career within the prestigious “Magic Circle” of global legal firms. He served as the Head of Tax at Clifford Chance, where he advised governments, central banks, and multinational corporations on the most intricate aspects of international tax law. His daily work involved navigating the labyrinthine statutes that govern global finance.
However, the global shifts of the early 2020s prompted him to re-evaluate his professional trajectory. In May 2022, he took the unconventional step of retiring from his lucrative partnership to launch Tax Policy Associates. This move was not driven by the need for traditional financial gain. Instead, he sought to create a platform that would improve tax policy while shaping the public debate around fiscal fairness.
From Big Law to Public Accountability
The creation of Tax Policy Associates marked a significant departure from his previous life. Most lawyers in his position would typically move into high-level corporate roles or judicial appointments. Conversely, he chose to focus his expertise on public advocacy. He recognized that the general public lacked a bridge between complex tax filings and understandable policy analysis.
Consequently, his organization began publishing deep-dive reports on critical issues. From the tax complications faced by postmasters in the Post Office scandal to the offshore share structures of high-profile ministers, his work provided a forensic level of scrutiny that was previously missing. This shift from private practice to public interest advocacy allowed him to apply his professional toolkit to a wider, societal benefit.
The Impact of Tax Policy Associates
Since its inception, the organization has grown into a vital clearinghouse for data-driven economic analysis. It consistently challenges the status quo by exposing loopholes and calling for meaningful institutional reform. By leveraging his deep industry expertise, he successfully demystifies technical financial narratives for journalists, politicians, and the average citizen.
Furthermore, his method involves “sunlight as the best disinfectant.” By making tax data accessible, he eliminates the ability for powerful entities to hide behind complexity. This approach has earned him both national respect and significant industry accolades, including awards for investigative journalism.
Deep Dive: The Ashley Hurst Dan Neidle Dispute
One of the most defining chapters in his recent career involves the ashley hurst dan neidle dispute, a case that reverberated through the British legal community. This matter centered on the boundaries of professional conduct, the usage of “without prejudice” labels, and the ethical responsibilities of legal representatives when dealing with investigative journalists.
Understanding the Legal Conflict
The conflict emerged during the height of the investigation into the former Chancellor’s tax affairs. Mr. Ashley Hurst, a partner at a prominent law firm, represented the minister and engaged with the investigator to seek a retraction of published allegations. The core of the tension lay in an email sent by Mr. Hurst, which was marked “Confidential & Without Prejudice.”
Our subject viewed this as an improper attempt to stifle legitimate reporting and suppress public interest information. Therefore, he declined to treat the correspondence as privileged and published it on his platform. This act triggered a disciplinary investigation by the Solicitors Regulation Authority (SRA) into Mr. Hurst’s conduct. The initial disciplinary tribunal found Mr. Hurst had improperly attempted to restrict publication, leading to fines and significant legal costs.
The High Court Ruling and Future Precedent
However, the matter did not conclude there. In early 2026, the High Court overturned the disciplinary tribunal’s decision, providing a critical clarification on legal privilege. The court emphasized that labeling correspondence is a recognized legal tool that must be respected, provided it is an arguable attempt to resolve a dispute.
The judgment clarified that the tribunal had incorrectly assumed a “right to publish” was an absolute defense against confidentiality claims. Consequently, the High Court ruling established that legal professionals acting for high-profile clients retain the right to utilize standard protective markers, as long as they are making a genuine attempt to settle a dispute. The ashley hurst dan neidle dispute serves as a landmark case, highlighting the delicate balance between a lawyer’s duty to their client and the public’s right to transparent governance.
Public Persona and Media Presence
Beyond his investigative reports, dan neidle has become a fixture in the modern media landscape. He frequently appears on high-profile broadcasts to discuss the state of the British economy and the mechanics of tax avoidance. His media presence is characterized by a pragmatic, non-partisan approach that avoids ideological grandstanding.
Why Listen to a Dan Neidle Podcast?
When listeners search for a dan neidle podcast appearance, they are usually treated to a deep dive into the “black box” of political finance. Whether he is a guest on The Rest is Money or hosting his own series like the BBC Radio 4 program Untaxing, he excels at breaking down complex topics.
These programs provide a unique opportunity to understand the mechanics behind tax policy. He often critiques the effectiveness of wealth taxes and offers concrete solutions for reforming the tax code. His conversational style—direct, analytical, and occasionally dry—resonates with audiences tired of political spin. Listeners appreciate his ability to transform boring statutory jargon into compelling, actionable insights.
The Discussion on Public Finance
In these discussions, he often argues for simpler, broader taxes rather than the current, fragmented system. He believes that the existing code is overly complex and favors those who can afford expensive advice. Consequently, his presence in the media helps maintain public pressure on policymakers to address these structural imbalances. He remains a key voice for those who believe the tax system should be a tool for economic stability rather than a mechanism for private shielding.
Clarifying the Dan Neidle Net Worth Myth
Questions regarding the dan neidle net worth often arise as a natural byproduct of his high-profile career transition. It is essential to understand that his financial standing is primarily the result of his long, successful tenure in top-tier corporate law. Serving as a partner at a Magic Circle firm involves substantial compensation, reflecting the high-stakes nature of international tax law.
Career Earnings vs. Non-Profit Mission
However, his current work with Tax Policy Associates is not a vehicle for personal accumulation. It is a mission-driven enterprise. Public curiosity about his wealth often stems from a desire to understand his motivations. People frequently wonder why someone at the peak of a lucrative legal career would walk away from it.
The answer, as evidenced by his body of work, is a fundamental shift in priority. He moved away from a role where his “capital” was measured in billable hours. Now, his influence is measured by the policy reforms he champions and the transparency he brings to government processes. While his exact personal valuation remains a private matter, his professional shift suggests that his current wealth is found in the impact of his work rather than a specific financial figure.
The True Value of His Investigative Work
The value he brings to the UK tax landscape extends far beyond personal finance. By dedicating his time to non-profit advocacy, he has effectively “donated” his expertise to the public. This shift has arguably yielded a higher return for the public interest than if he had remained in private practice. His willingness to sacrifice potential corporate earnings to pursue accountability demonstrates a rare commitment to the public good.
The Future of UK Tax Oversight
As of mid-2026, the influence of his work continues to expand. Tax Policy Associates remains a leading independent think tank, providing high-quality, free-to-access analysis on tax law. Their work covers a wide array of topics, from stamp duty reform to investigating procurement abuses.
Challenging Institutional Norms
One of the core strengths of his approach is the ability to translate dense, impenetrable language into accessible content. By publishing clear charts and infographics, his team keeps complex issues within the national news cycle. He effectively forces policymakers to address the concerns of the electorate.
Moreover, his engagement with the legal community ensures that the standards for public accountability are consistently refined. By questioning the status quo, he encourages a healthier debate about what constitutes “fair” tax practices. He has established a blueprint for how independent experts can challenge institutional inertia effectively.
Long-term Vision for Tax Reform
Looking forward, his focus will likely remain on structural simplification. He has consistently argued that the UK’s tax system is suffering from “complexity creep.” When the government adds new rules and exemptions, the system becomes increasingly unfair and difficult to enforce.
Consequently, his advocacy for a streamlined system is not just about convenience; it is about economic growth. If the system is easier to navigate, it is also harder to abuse. By maintaining his focus on these technical reforms, he ensures that the discourse remains centered on practical improvements rather than partisan bickering.
Conclusion
The career of dan neidle serves as a powerful testament to the impact of directed expertise. From his roots as a top-tier tax lawyer to his current role as a vigilant watchdog, he has redefined the role of a modern policy advocate. He has proven that domain knowledge is a potent tool for societal change.
His work reminds us that challenging institutional power does not always require loud protests. Sometimes, it simply requires a better understanding of the rules by which that power operates. By demystifying the tax code, navigating complex legal disputes, and remaining steadfast in his commitment to transparency, he has secured his place as a consequential figure in British fiscal discourse.
As the landscape of international finance continues to evolve, the impact of his work will undoubtedly continue to influence how the public, the press, and the government interact with tax policy. Transparency is the only viable path forward, and he continues to lead that charge with rigorous analysis and persistent, principled investigation.
